14 September 2026
VAT Registration Belgium
Companies set up in Belgium must file for VAT registration; our company formation specialist can assist you in the process of VAT registration in Belgium.
Value added tax (VAT) is an indirect tax in Belgium with a standard rate of 21% for certain goods and services commercialized on the Belgian territory. Our company formation agents can provide you with further information on VAT registration in Belgium, compulsory for all businesses set up here.
| Quick Facts | |
|---|---|
| We offer VAT registrationservices | yes |
Standard rate | 21% |
Lower rates | 0%, 6%, 12% |
| Who needs VAT registration | All companies engaged in activities subject to VAT, before the commencement of such activities |
| Time frame for registration | Approximately 4 weeks |
| VAT for real estate transactions | The purchase of new real estate can be subject to the 21% VAT rate; exemptions apply |
| Exemptions available | A VAT exemption scheme applies to small businesses in Belgium with an annual turnover of less than EUR 25,000 |
| Period for filing | Monthly or quarterly |
| VAT returns support | Upon request |
| VAT refund | VAT deductions are available for most categories of business purchases; Certain categories of expenses do not qualify for a VAT refund (such as the supply and intra-Community acquisition of tobacco and alcoholic products). |
| Local tax agent required | Advisable |
| Who collects the VAT | Federal Public Service Finance |
| Documents for VAT registration | Registration form Company documents Proof of VAT-related activities Power of attorney if submitting the registration through a representative |
| VAT number format | BE + 8 digits + 2 check digits |
| VAT de-registration situations | When the company ceases its activities |
| Fiscal representative for non-EU businesses (YES/NO) | YES |
Voluntary registration | Only persons carrying out an economic activity can register; small businesses eligible for the exemption scheme may opt for normal VAT registration |
VAT registration for sole traders | Mandatory if engaging company is selling taxable goods/services; However, one exemption might apply if annual turnover is below 25,000 euros. |
| VAT registration for liaison offices (YES/NO) | NO |
| VAT for e-commerce activities | Mandatory, as per the European Union’s VAT regulations scheme |
| Threshold for e-commerce VAT registration | More than 10,000 euros in annual net sales |
| Record-keeping requirements | 10 years |
| Invoice must contain VAT rate (YES/NO) | YES |
| Other invoice requirements | – invoice number, – date of issuance, – customer and supplier information, – description of goods/services, total amount, etc.; since 1 January 2026, B2B invoices between businesses established in Belgium must be structured electronic invoices (Peppol) |
| Simplified invoices | For goods/services below 125 euros. |
| Penalties for late VAT payments | Since 1 May 2026: a fine of 5% of the unpaid VAT (10% if the return was also filed late, 15% in case of a substitute return) if not paid by the 10th of the month after the due date, plus late-payment interest at the annual statutory rate. |
| Number of double taxation treaties | About 95 in force |
| Deadline for VAT payments | By the 20th of the following month for monthly filers and by the 25th of the month following the quarter for quarterly filers |
| Reverse charge mechanism | The customer can be responsible for reporting and paying the VAT. |
| Other available services | We also assist in company formation. |
What services you offer on VAT registration in Belgium?
VAT registration in Belgium is included in the list of compulsory registrations that are performed by us during the creation of a Belgian company. Among the compulsory registrations are Crossroads Bank for Enterprises (CBE), EORI, and others. We will be able to help entrepreneurs with the following services:
- prepare all the necessary information for VAT registration;
- consider the activities of the company which are planned;
- register the company for VAT;
- assist foreign entrepreneurs in understanding the rules of VAT registration in Belgium.
How can I register for VAT in Belgium?
Registration for VAT purposes in Belgium is possible in the following ways:
- with the local VAT administration office, as soon as the company has recorded the transaction that is subject to this tax, or before the commencement of the activities if it is certain that these will be subject to VAT;
- via an approved enterprise counter (guichet d’entreprises/ondernemingsloket), a type of business office that can be found in various locations around the country and allows businesses to perform a set of mandatory registrations and activities.
Which are the steps to register for VAT in Belgium in 2026?
Obtaining the VAT in Belgium is subject to the following four steps:
- company registration: before registering for VAT purposes, the company needs to be registered with the Crossroads Bank for Enterprises (Banque-Carrefour des Entreprises – BCE)
- form filling: the company is then required to fill in form 604A and submit it to the competent authorities.
- examination: the form is examined by the authorities and once this is complete, the business number that has been attributed by the BCE is also approved as a VAT identification number.
- notice: the authorities communicate the VAT registration result to the taxable company or individual via a formal letter.
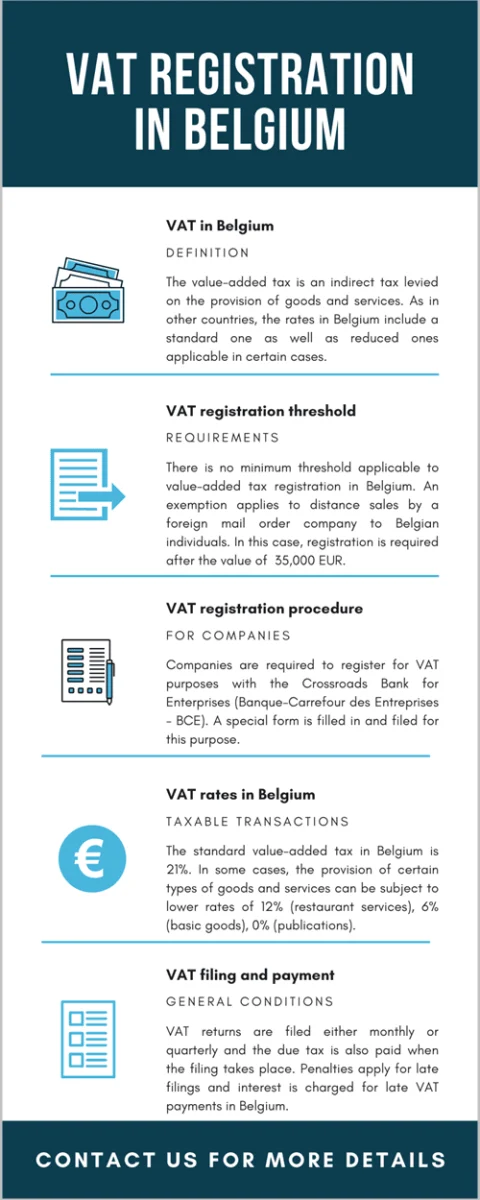
Below, you can find more information on VAT registration in Belgium, from this infographic:
Which are the requirements to be taxed for VAT purposes in Belgium?
According to the Belgian tax law, a taxable individual for VAT purposes is a natural or legal person that:
- exercises an economic activity;
- in an independent and habitual manner;
- as the main activity or a secondary activity;
- for the purpose of delivering goods or services covered by the VAT code and regardless of the economic activity that takes place for the actual provision of these goods and services.
What information is needed for VAT registration in Belgium in 2026?
Entrepreneurs should be ready to provide the following information:
- identification details of the organization;
- taxable activities to be conducted by the organization;
- date of start of the activities;
- annual turnover anticipated; and
- details necessary for determination of the applicable VAT system.
Do foreign companies need to register for VAT in Belgium?
Yes, like a locally registered company, a foreign company registered for VAT in Belgium is subject to the following when carrying out activities that are not subject to a VAT exemption (as per Article 44 of the VAT Code):
- identify the VAT obligations that arise, before the start of the activities;
- submit the VAT statements;
- return the invoiced VAT to the customers;
- file the annual client listing;
- hold proper accounts and issue proper invoices.
What are the VAT rates in Belgium in 2026?
Below, we present the VAT rates in Belgium:
- 21%: this is the standard value-added tax, applicable to a wide range of goods and services
- 12%: applied to foodstuffs, agricultural products, social housing, catering industry, hotel and camping accommodation (since 1 March 2026) and several minerals used as energy products;
- 6%: applied to foodstuffs, water, medicaments, medical equipment designed for persons with physical disabilities, transportation (for passengers), books and cultural events; our company formation specialists can provide you with a detailed list of services and products in this category;
- • 0% for daily and weekly publications and some recycled goods.
We invite you to watch the following video on VAT registration requirements:
Are there any VAT exemptions in Belgium?
Yes, although companies are required to pay VAT and submit the monthly statements, however, this is not mandatory for companies that do not exceed a certain annual turnover.
- the tax exemption scheme: for small businesses with an annual turnover of no more than 25,000 euros;
- the agricultural regime: the farmer benefits from exemptions from most of the obligations that arise under the normal regime; there is no need to file the VAT statements and does not pay VAT (thus he cannot deduct it).
- the margin tax system: applicable to works of art, collectibles, antiques or second-hand goods.
What is the price for VAT registration in Belgium?
- VAT registration in Belgium is a part of our company formation package, priced at €2,300 + VAT;
- Also, the VAT registration process alone costs betweeen EUR60 – EUR85 + VAT.
Our company formation package will include the preparation of the incorporation documentation, financial plan, and other mandatory registrations, such as: VAT, EORI, UBO, and CBE.
If you need further details on the VAT legislation applicable in Belgium, please contact our company formation representatives, who can offer assistance according to your business plan and can help you in the process of VAT registration in Belgium.